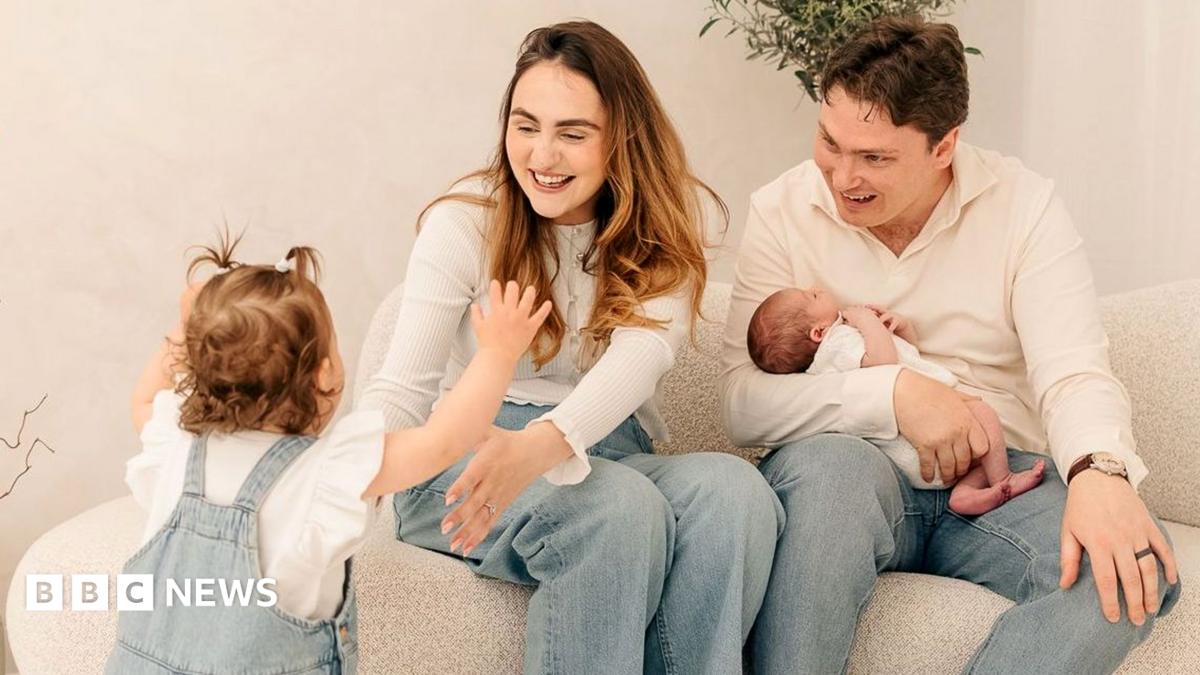
Pensions for children, also called Junior self-invested personal pensions (SIPPs), were introduced in the UK in 2001. You can pay in a maximum of £2,880 per year, which the government will then top up with £720 tax relief to make a total £3,600.
The popularity of Junior SIPPs has grown, industry figures show.
One provider, Hargreaves Lansdown, says that in the 12 months to April 2026 it had seen two and a half times as many accounts open, external as in the same period a year earlier.
Another, Fidelity, says it has seen the number of accounts more than triple since December 2023.
While giving their kids a pensions head start is a powerful incentive for some parents, how do the children themselves feel about not being able to touch the money for potentially 50 years or more?
Fifteen-year-old Hugo Thompson from Manchester seems unfazed. His parents, who work in finance, have been paying the maximum amount into his Junior SIPP for the past 10 years.
“The money invested means perhaps I’ll be ahead when I’m older,” he says. “So I won’t have to put quite so much of my own money in! I want to retire earlier than the state pension age so this will all help.”
Hugo’s mother Annabel, who works in finance, also saves into a Junior ISA for him, but says she still also invests into her own pension and savings. “For me, Junior SIPPs should only be considered once you feel you have enough money of your own,” she says.